Brand new FHA prepared several months immediately following case of bankruptcy and you can property foreclosure initiate regarding registered time or perhaps the date of sheriff’s property foreclosure marketing and you may deed-in-lieu from foreclosure. Also, discover a good around three-seasons wishing months in the quick income go out and on date from home financing charge-out-of otherwise 2nd mortgage fees-off to qualify for FHA mortgage brokers. Lenders and stress the significance of avoiding late costs immediately after a foreclosures, deed-in-lieu of property foreclosure, or quick selling.
It is a common myth you to a prior bankruptcy proceeding, property foreclosure, deed-in-lieu out-of property foreclosure, otherwise small deals tend to end in highest home loan rates, such as for instance of FHA money. Alex Carlucci, an elder mortgage officer and you may team commander at Gustan Cho Partners, clarifies this new perception ones incidents to your mortgage costs, especially bringing-up the newest FHA waiting months immediately after bankruptcy and you may foreclosure:
Contrary to belief, a case of bankruptcy otherwise foreclosure cannot affect the rates out of financial pricing on the FHA money, neither have there been loan-level costs changes predicated on such situations having FHA money.
Fico scores will be top determinant of home loan cost for FHA fund. However, traditional funds envision credit scores and you may mortgage-to-well worth rates getting rate devotion. Previous bankruptcy or property foreclosure will not change the rates of interest individuals located for the FHA prepared period after bankruptcy proceeding and foreclosures. There are no rates adjustments of these occurrences into FHA financial pricing.
What are the Benefits associated with a keen FHA Loan?
Given that a good example, immediately after a chapter 7 bankruptcy release, you could potentially qualify for an FHA financing in as little as two years, and you will just after a property foreclosure, you will be qualified in 3 years. Alot more flexible underwriting recommendations: Brand new FHA enjoys even more lenient underwriting standards than just antique loan providers and get believe compensating issues such as your employment record, deals, reserves, otherwise commission records when contrasting the loan application.
What are the Cons from a keen FHA Mortgage?
A keen FHA loan has specific disadvantages you need to know just before applying. Any of these disadvantages try High mortgage insurance fees: You’re going to have to shell out each other an initial and you may an annual financial top to possess an enthusiastic FHA loan, which can add to the monthly installments and you can closing costs.
You are going to need to afford the annual MIP toward lifestyle of mortgage or perhaps 11 years, based your down payment and you may financing identity, while you could terminate the non-public mortgage insurance policies (PMI) to have a normal mortgage once you achieved 20% security of your home.
FHA fund has actually lower financing limitations than conventional finance. The amount Maryland personal loans you could obtain having a keen FHA mortgage was subject to help you limitations set from the FHA, hence are different with regards to the state and type out of assets. As a result, in certain parts, some think it’s difficult to buy a high priced family having fun with a keen FHA financing.
HUD Possessions Conditions Having FHA Funds
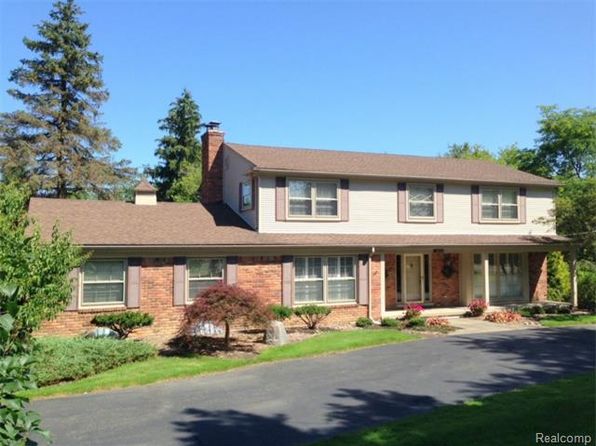
Assets updates criteria to the FHA finance will be the possessions needs to end up being safer, habitable, and safe. HUD has actually rigorous requirements toward position and you may top-notch the fresh new assets you want to pick with an enthusiastic FHA financing. The house or property need to meet the minimal assets standards (MPRs) and you can admission an appraisal by the a keen FHA-accepted appraiser.
Brand new MPRs security certain areas of the house, such shelter, safety, soundness, and practices. If the assets will not meet up with the MPRs, you might have to ask owner and also make fixes or explore an excellent 203(k) loan to invest in the fresh new solutions.
Conventional Instead of FHA Waiting Several months After Bankruptcy and you may Foreclosure
An enthusiastic FHA financing allows you to be eligible for a home loan sooner with less stringent criteria than just a traditional loan. Check out samples of exactly how an FHA mortgage may help you order a house once more borrowing situations. An FHA loan has numerous advantages for borrowers with a credit skills or any other demands inside the being qualified having a traditional mortgage.